.
SEO OMP
administrator
Blog posts:41
Join date:
Jul 6, 2026
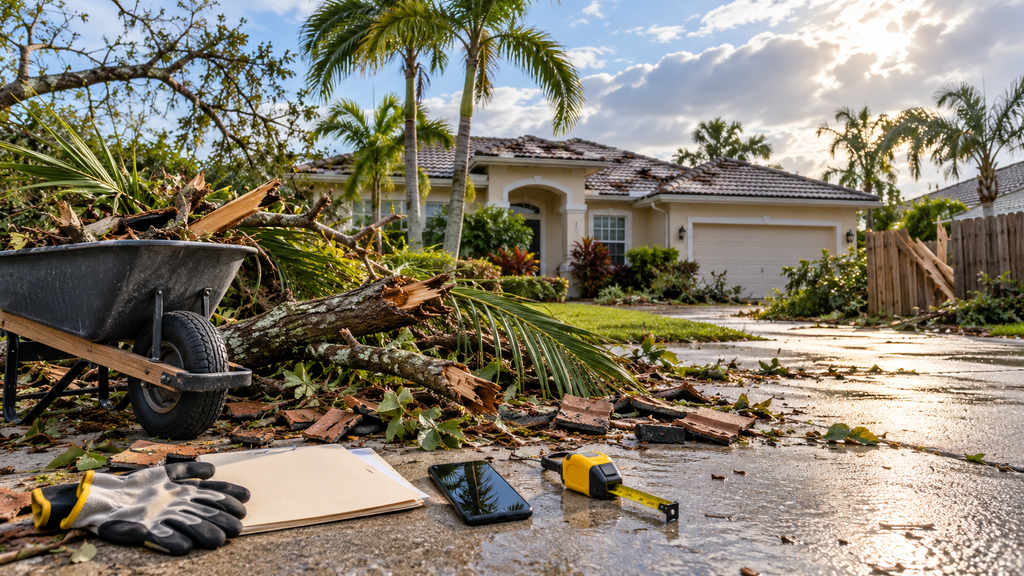
Does Homeowners Insurance Cover Debris Removal After a Storm?
After a hurricane or severe storm in Florida, your property may be covered with fallen branches, broken roofing materials, damaged fencing, and other debris. While cleaning up the damage is important, many homeowners face another question: Does homeowners insurance cover debris removal after a storm? In many cases, homeowners insurance may cover debris removal when the debris results from a covered property loss. However, not every cleanup expense qualifies for reimbursement. Coverage depends on what caused the damage, whether insured property was affected, and the specific terms and limits of your policy. At PICC FLA, we help Florida property owners navigate insurance claims involving hurricanes, wind, roof damage, and other property losses. We understand that storm recovery involves more than repairing a damaged building. Property owners may also need to address fallen trees, damaged building materials, and debris that must be removed before repairs can begin. In this guide, we explain when debris removal may be covered, how tree debris...
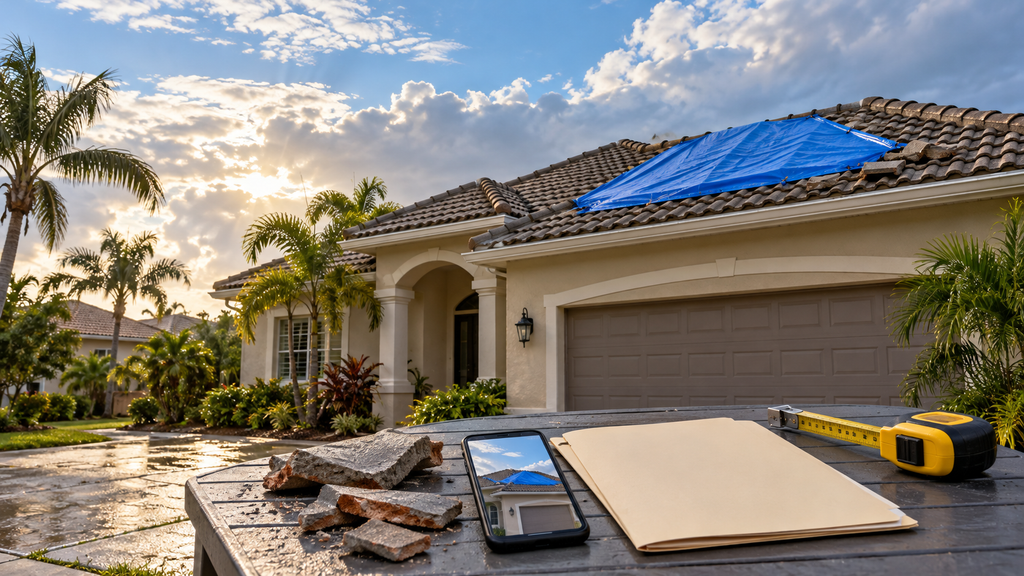
Will Insurance Pay for Emergency Roof Tarping?
After a hurricane or severe storm in Florida, roof damage can leave your home exposed to additional rain, wind, and water intrusion. When shingles are missing, roofing materials are damaged, or an opening appears in the roof, installing a temporary tarp may be necessary to protect the property. But will insurance pay for emergency roof tarping? In many cases, homeowners insurance may cover reasonable emergency roof tarping expenses when the work is necessary to prevent additional damage following a covered loss. However, reimbursement is not automatic. Coverage depends on the cause of the roof damage, the terms of your insurance policy, the necessity of the temporary repairs, and the documentation supporting the expenses. At PICC FLA, we help Florida homeowners navigate insurance claims involving hurricanes, wind, roof damage, and water intrusion. We understand that protecting your property cannot always wait until an insurance adjuster arrives. In this guide, we explain how emergency roof tarp insurance works, when temporary repairs may...
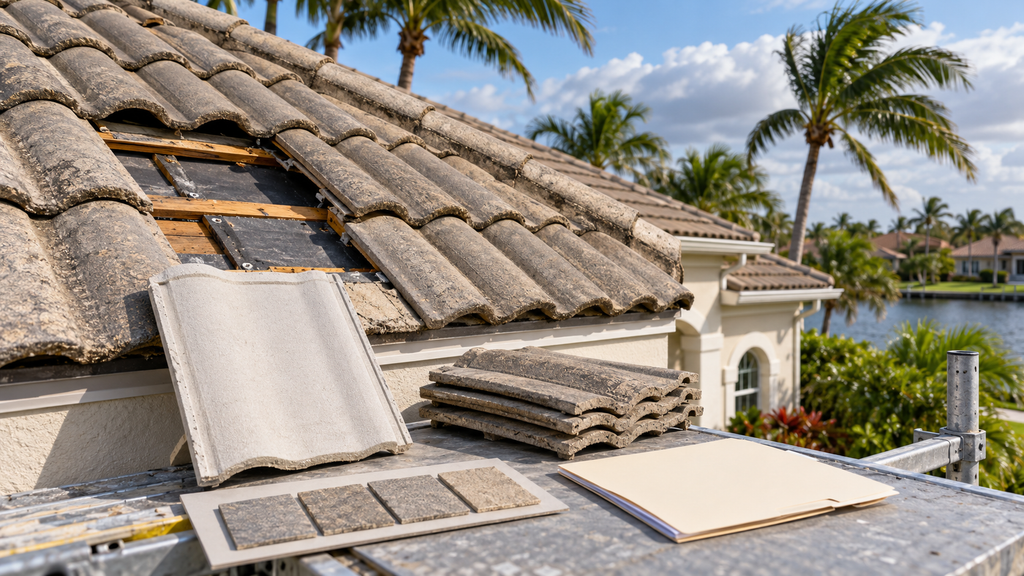
What Is Florida’s Matching Rule for Property Insurance Repairs?
After property damage, homeowners often expect their insurance company to pay for repairs that restore their home to its previous condition. But what happens when new flooring, roofing materials, cabinets, or wall finishes no longer match the existing materials? This is where Florida’s matching rule for property insurance repairs becomes important. Under Florida Statutes Section 626.9744, insurers may be required to make reasonable repairs or replacements in adjoining areas when replacement items do not match existing items in quality, color, or size. However, the rule does not automatically guarantee replacement of an entire room, floor, or roof. At PICC FLA, we help Florida homeowners understand their property insurance claims, document damage, review repair estimates, and address disagreements involving repair costs and the scope of work. We believe homeowners should understand how matching requirements may affect their claims before accepting an insurance estimate. Our property insurance claim process explains how inspections, documentation, estimates, and negotiations fit into a property damage claim....
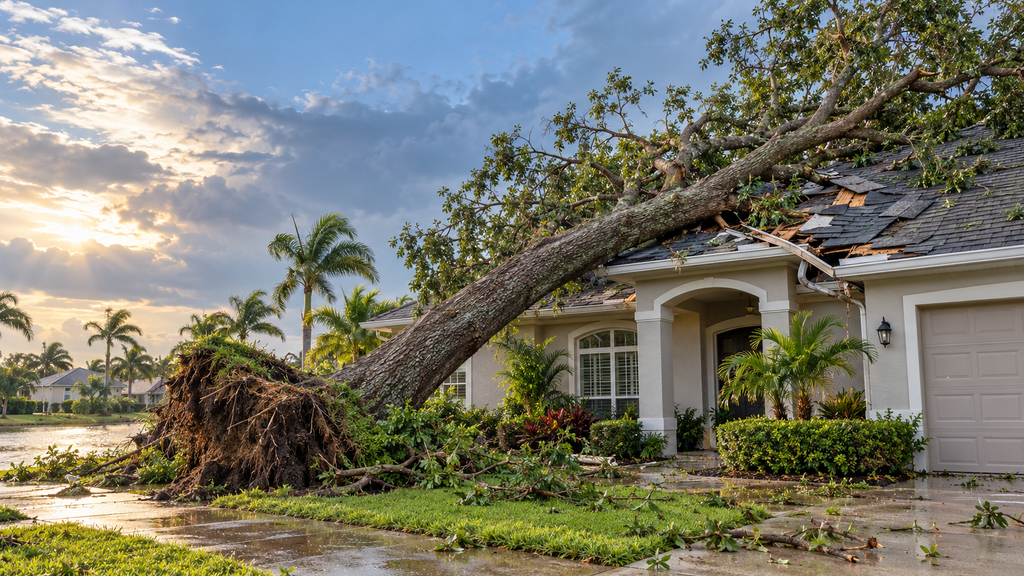
Does Homeowners Insurance Cover a Fallen Tree?
A severe Florida storm can turn a healthy-looking tree into a major property loss in seconds. Heavy wind, hurricanes, lightning, and other weather events can send a tree or large branch onto a roof, garage, fence, or another part of a property. That usually leaves homeowners with an urgent question: Does homeowners insurance cover a fallen tree? The answer depends on what caused the tree to fall, what it damaged, and what your specific policy covers. In many situations, homeowners insurance can cover damage to insured property when a tree falls because of a covered event. Tree and debris removal may also be covered when the fallen tree damages insured property, although policy limits can apply. At PICC FLA, we assist Florida homeowners with property claims involving fallen objects, wind damage, hurricanes and storms, roof damage, and other property losses within the scope of our services. When a tree damages a home, we focus on documenting the full property loss,...
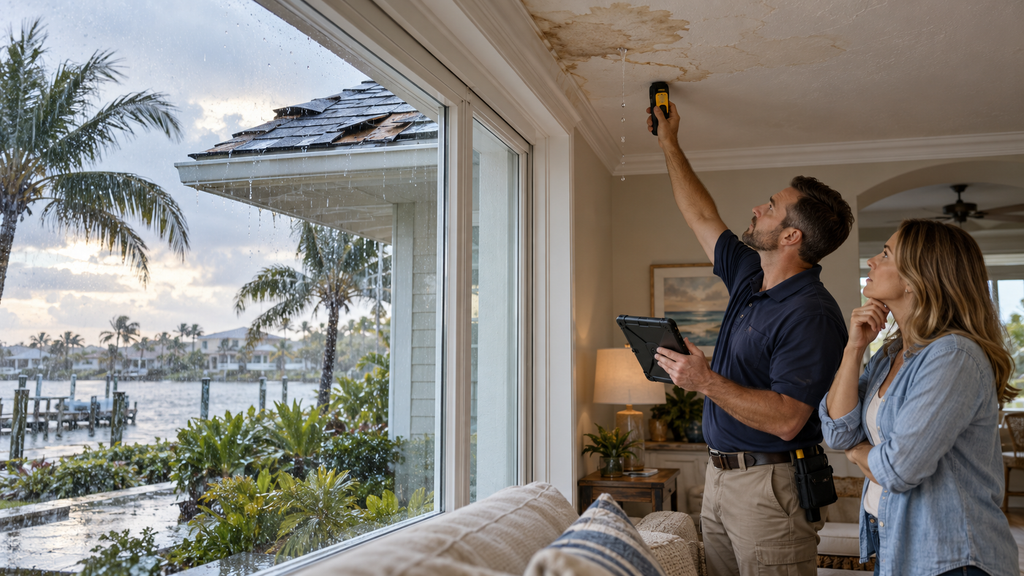
Does Homeowners Insurance Cover Wind-Driven Rain?
Florida storms can bring heavy rain and powerful winds at the same time. When water suddenly appears on a ceiling, runs down an interior wall, or reaches flooring after a storm, one of the first questions homeowners ask us is: Does homeowners insurance cover wind-driven rain? The answer depends on how the rain entered the property and what your policy covers. In Florida, hurricane coverage includes certain interior rain damage when the direct force of a windstorm first damages the building and creates an opening through which rain enters. However, not every situation involving rain entering a home is automatically covered. The specific policy language, cause of damage, condition of the property, exclusions, endorsements, and circumstances of the loss all matter. At PICC FLA, we help Florida property owners document and navigate claims involving wind, hurricanes, roof damage, water intrusion, and other property losses. When rain enters a home during a storm, one of our priorities is identifying what happened...
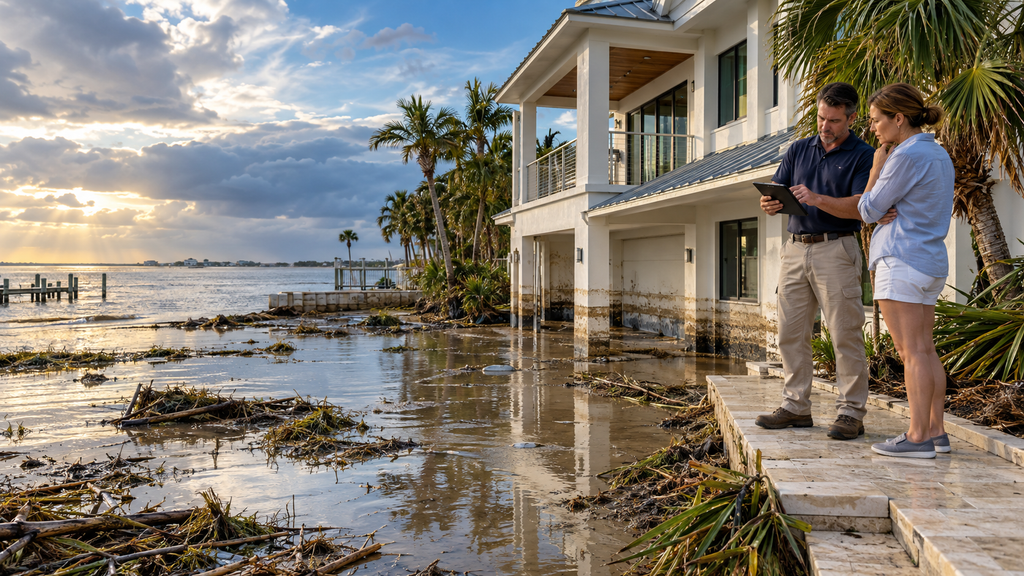
Does Homeowners Insurance Cover Storm Surge?
When a hurricane approaches Florida, homeowners naturally think about wind, rain, roof damage, and flooding. But one of the most destructive hurricane hazards can be storm surge. This raises an important insurance question: Does homeowners insurance cover storm surge? In most cases, standard homeowners insurance does not cover flood damage caused by storm surge. Storm surge is generally treated as flooding, so coverage for that type of loss usually comes from a separate flood insurance policy rather than a standard homeowners policy. At PICC FLA, we help Florida property owners document and navigate property insurance claims involving hurricanes, floods, wind, roof damage, water intrusion, and other covered losses. When a hurricane causes several types of damage at the same property, determining how each part of the damage occurred can be an important part of the claims process. That distinction matters because a hurricane can cause wind damage and flood damage during the same event, but those losses may fall under...
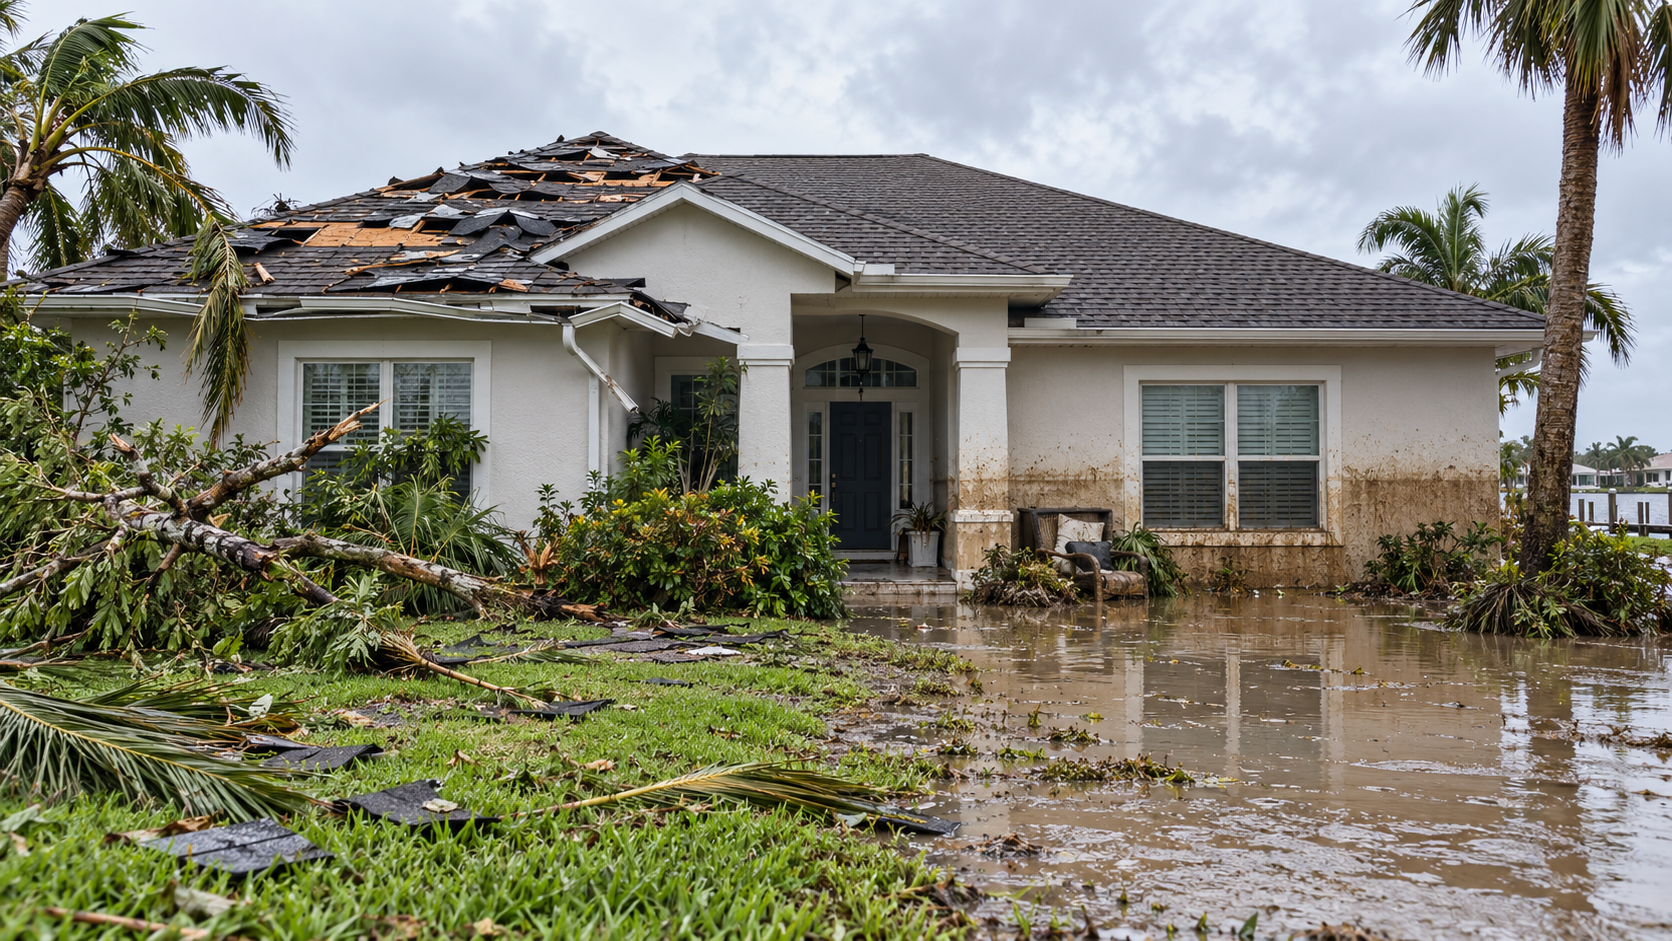
How Can You Tell Wind Damage From Flood Damage After a Hurricane?
After a hurricane, water inside your home does not automatically mean you have flood damage. A storm can damage a roof, break a window, tear away exterior materials, or create another opening that allows rain to enter. At the same time, storm surge, overflowing waterways, and rapidly accumulating surface water can cause a separate type of loss classified as flooding. Understanding the difference matters because wind and flood losses can be treated differently under insurance policies. At PICC FLA, we help Florida property owners document and assess hurricane, wind, flood, roof, and water damage claims. When a hurricane causes several types of damage at once, we focus on identifying how the damage occurred and documenting the full scope of the loss before the claim is presented. What Is the Main Difference Between Wind Damage and Flood Damage? The simplest distinction is the source and path of the damage. Wind damage generally begins when strong winds directly damage the building or...
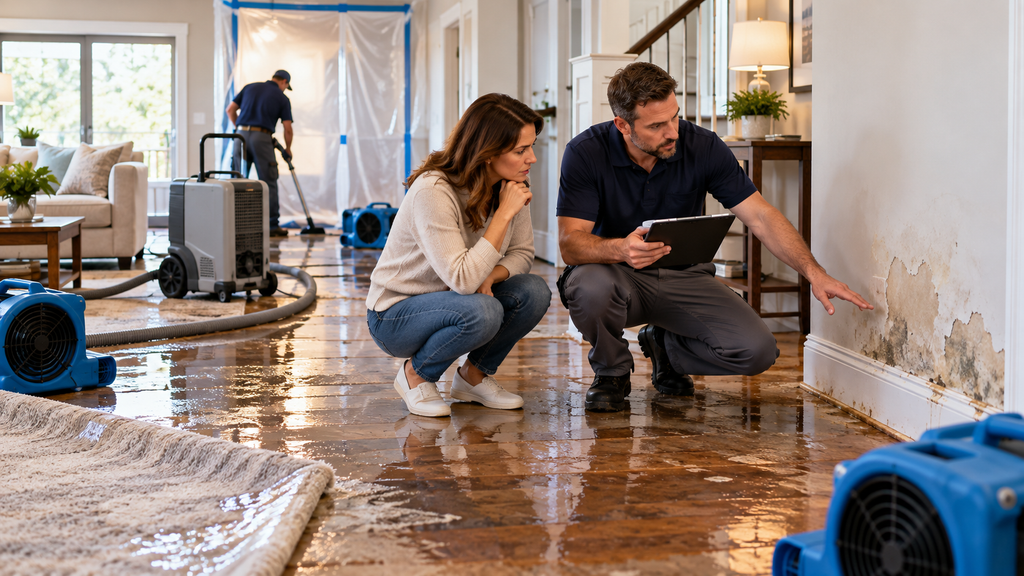
What Water Mitigation Costs Can Be Included in an Insurance Claim?
When water enters your home or commercial property, stopping the damage is usually one of the first priorities. Removing standing water, drying affected areas, and preventing moisture from spreading can help protect the property while the insurance claim is being evaluated. But which of those expenses can actually be included in a water mitigation insurance claim? At PICC, we help Florida property owners document, assess, present, and negotiate property insurance claims. Water mitigation expenses may be part of a covered water damage claim when the work is reasonable, necessary, related to the covered loss, and supported by proper documentation. However, coverage is never automatic. Your policy language, the cause of the water damage, applicable limits, your deductible, and the circumstances of the loss all matter. If you are dealing with water damage, our Florida public adjusters can help you understand the claim process and determine what documentation may be needed. What Does Water Mitigation Mean in an Insurance Claim? Water...
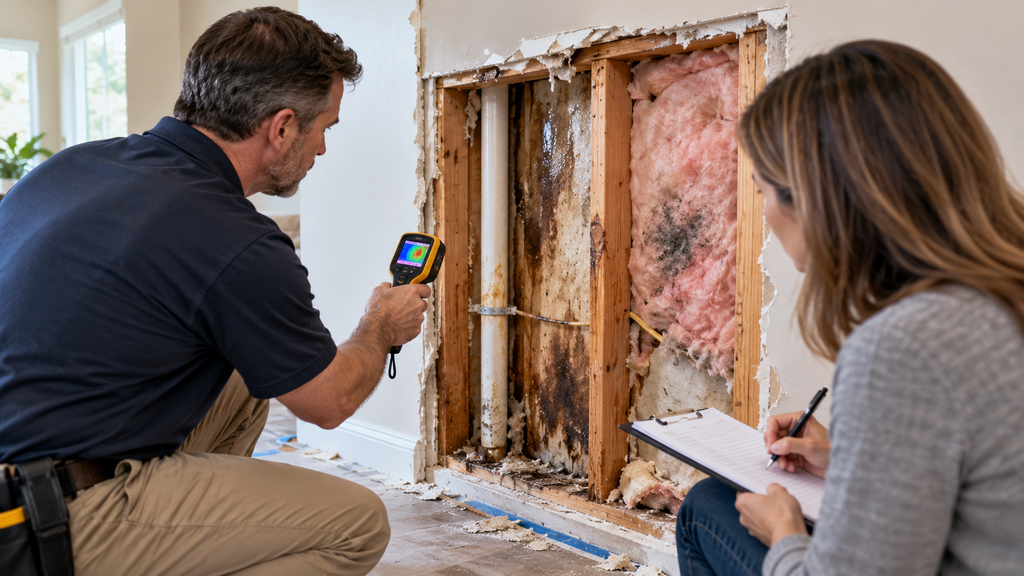
How Do You Prove Hidden Water Damage in an Insurance Claim?
Hidden water damage can be difficult to deal with because the most serious problems are not always visible when you first discover the loss. A ceiling stain may seem minor, but moisture could have reached insulation, drywall, flooring, cabinets, or other concealed areas. A leaking pipe may stop dripping, while water remains trapped behind a wall. So, how do you prove hidden water damage in an insurance claim? At PICC FLA, we focus on documenting the full extent of property damage, including damage that may have been missed during an initial inspection. Proving hidden water damage generally requires connecting the concealed damage to the reported loss and supporting that connection with detailed inspections, photographs, videos, estimates, repair findings, and other available documentation. A strong hidden water damage insurance claim is not based on assumptions. It is built around evidence showing what happened, where the water traveled, what property was affected, and what repairs are reasonably associated with the documented loss....