Florida Property Insurance Claim Guides and Public Adjuster Resources
Condo Master Policy vs HO-6: How Do Claims Work Together?
When your condominium suffers property damage, figuring out which insurance policy should cover the repairs can be confusing. Unlike a single-family home, a condominium generally involves two separate insurance policies: the condominium association’s master policy and your individual HO-6 policy. Understanding condo master policy vs. HO-6 insurance is important because both policies may be relevant after the same property loss. However, they typically cover different parts of the property. For example, a hurricane may damage the condominium’s roof and allow rainwater to enter your unit. The association’s master policy may cover qualifying roof and building damage, while your HO-6 policy may cover damaged interior finishes, cabinets, and personal belongings. At PICC FLA, we help Florida condominium owners navigate property insurance claims involving water damage, hurricanes, roof damage, and other property losses. We understand that condo claims become complicated when multiple insurance policies and repair responsibilities are involved. In this guide, we explain how the two policies work together, which property...
Who Is Responsible for Water Damage in a Florida Condo?
Water damage in a Florida condominium can quickly become complicated. A leaking pipe, overflowing appliance, damaged roof, or plumbing failure in another unit can leave you with wet ceilings, damaged flooring, and expensive repairs. When this happens, one of the first questions you may ask is: Who is responsible for water damage in a Florida condo? The answer depends on what caused the damage, which parts of the property were affected, and how responsibility is divided between the condominium association and individual unit owners. In Florida, condominium associations generally insure certain building components and common property, while individual owners are responsible for insuring specified interior finishes, improvements, and personal belongings. However, negligence, governing documents, and the circumstances of the loss can affect who ultimately pays. At PICC FLA, we help Florida condominium owners navigate property insurance claims involving plumbing leaks, water intrusion, roof damage, hurricanes, and other property losses. We understand that dealing with water damage becomes more difficult when...
What Is Loss Assessment Coverage for Condo Owners?
Owning a condominium in Florida comes with responsibilities beyond maintaining your individual unit. You also share ownership of common property, such as roofs, hallways, elevators, and other building components. When a hurricane, fire, or another unexpected event damages these shared areas, the condominium association may need to collect money from unit owners to cover certain expenses. This is where condo loss assessment coverage becomes important. Loss assessment coverage is a feature of condominium unit owners insurance that may help pay qualifying assessments charged by a condominium association following covered property damage. However, not every special assessment qualifies for insurance coverage. At PICC FLA, we help Florida condominium owners navigate property insurance claims involving storm damage, water damage, fire damage, and other property losses. We understand that condominium claims can become complicated when an individual unit owner’s policy and the association’s master insurance policy are both involved. Understanding how loss assessment coverage works can help you review an unexpected assessment, identify...
Condo Insurance vs HOA Insurance: Who Covers What?
Owning a condominium in Florida means sharing certain responsibilities with your condominium association. But when a hurricane damages the roof, a pipe leaks between units, or water ruins your flooring, determining who should handle the insurance claim can become confusing. One of the most common questions we hear is: Condo insurance vs HOA insurance, who covers what? The short answer is that the condominium association’s master insurance policy generally covers the building’s structure and common property, while an individual condo owner’s HO-6 policy helps protect personal belongings, designated interior components, and personal liability. However, the division of coverage is not always as simple as separating everything inside your unit from everything outside. At PICC FLA, we help Florida condominium owners navigate property insurance claims involving water damage, roof leaks, hurricanes, storms, and other property losses. We review policy information, document damage, and help policyholders understand the claims process. Understanding the difference between these policies can help you determine where to...
Does Homeowners Insurance Cover Debris Removal After a Storm?
After a hurricane or severe storm in Florida, your property may be covered with fallen branches, broken roofing materials, damaged fencing, and other debris. While cleaning up the damage is important, many homeowners face another question: Does homeowners insurance cover debris removal after a storm? In many cases, homeowners insurance may cover debris removal when the debris results from a covered property loss. However, not every cleanup expense qualifies for reimbursement. Coverage depends on what caused the damage, whether insured property was affected, and the specific terms and limits of your policy. At PICC FLA, we help Florida property owners navigate insurance claims involving hurricanes, wind, roof damage, and other property losses. We understand that storm recovery involves more than repairing a damaged building. Property owners may also need to address fallen trees, damaged building materials, and debris that must be removed before repairs can begin. In this guide, we explain when debris removal may be covered, how tree debris...
Will Insurance Pay for Emergency Roof Tarping?
After a hurricane or severe storm in Florida, roof damage can leave your home exposed to additional rain, wind, and water intrusion. When shingles are missing, roofing materials are damaged, or an opening appears in the roof, installing a temporary tarp may be necessary to protect the property. But will insurance pay for emergency roof tarping? In many cases, homeowners insurance may cover reasonable emergency roof tarping expenses when the work is necessary to prevent additional damage following a covered loss. However, reimbursement is not automatic. Coverage depends on the cause of the roof damage, the terms of your insurance policy, the necessity of the temporary repairs, and the documentation supporting the expenses. At PICC FLA, we help Florida homeowners navigate insurance claims involving hurricanes, wind, roof damage, and water intrusion. We understand that protecting your property cannot always wait until an insurance adjuster arrives. In this guide, we explain how emergency roof tarp insurance works, when temporary repairs may...
What Is Florida’s Matching Rule for Property Insurance Repairs?
After property damage, homeowners often expect their insurance company to pay for repairs that restore their home to its previous condition. But what happens when new flooring, roofing materials, cabinets, or wall finishes no longer match the existing materials? This is where Florida’s matching rule for property insurance repairs becomes important. Under Florida Statutes Section 626.9744, insurers may be required to make reasonable repairs or replacements in adjoining areas when replacement items do not match existing items in quality, color, or size. However, the rule does not automatically guarantee replacement of an entire room, floor, or roof. At PICC FLA, we help Florida homeowners understand their property insurance claims, document damage, review repair estimates, and address disagreements involving repair costs and the scope of work. We believe homeowners should understand how matching requirements may affect their claims before accepting an insurance estimate. Our property insurance claim process explains how inspections, documentation, estimates, and negotiations fit into a property damage claim....
Does Homeowners Insurance Cover a Fallen Tree?
A severe Florida storm can turn a healthy-looking tree into a major property loss in seconds. Heavy wind, hurricanes, lightning, and other weather events can send a tree or large branch onto a roof, garage, fence, or another part of a property. That usually leaves homeowners with an urgent question: Does homeowners insurance cover a fallen tree? The answer depends on what caused the tree to fall, what it damaged, and what your specific policy covers. In many situations, homeowners insurance can cover damage to insured property when a tree falls because of a covered event. Tree and debris removal may also be covered when the fallen tree damages insured property, although policy limits can apply. At PICC FLA, we assist Florida homeowners with property claims involving fallen objects, wind damage, hurricanes and storms, roof damage, and other property losses within the scope of our services. When a tree damages a home, we focus on documenting the full property loss,...
Does Homeowners Insurance Cover Wind-Driven Rain?
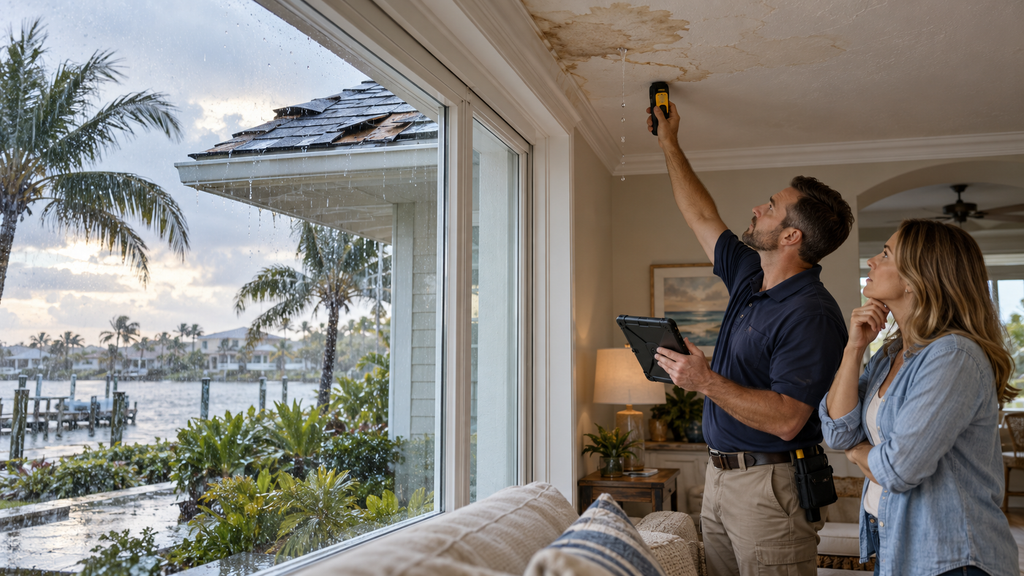
Florida storms can bring heavy rain and powerful winds at the same time. When water suddenly appears on a ceiling, runs down an interior wall, or reaches flooring after a storm, one of the first questions homeowners ask us is: Does homeowners insurance cover wind-driven rain? The answer depends on how the rain entered the property and what your policy covers. In Florida, hurricane coverage includes certain interior rain damage when the direct force of a windstorm first damages the building and creates an opening through which rain enters. However, not every situation involving rain entering a home is automatically covered. The specific policy language, cause of damage, condition of the property, exclusions, endorsements, and circumstances of the loss all matter. At PICC FLA, we help Florida property owners document and navigate claims involving wind, hurricanes, roof damage, water intrusion, and other property losses. When rain enters a home during a storm, one of our priorities is identifying what happened...
Does Homeowners Insurance Cover Storm Surge?
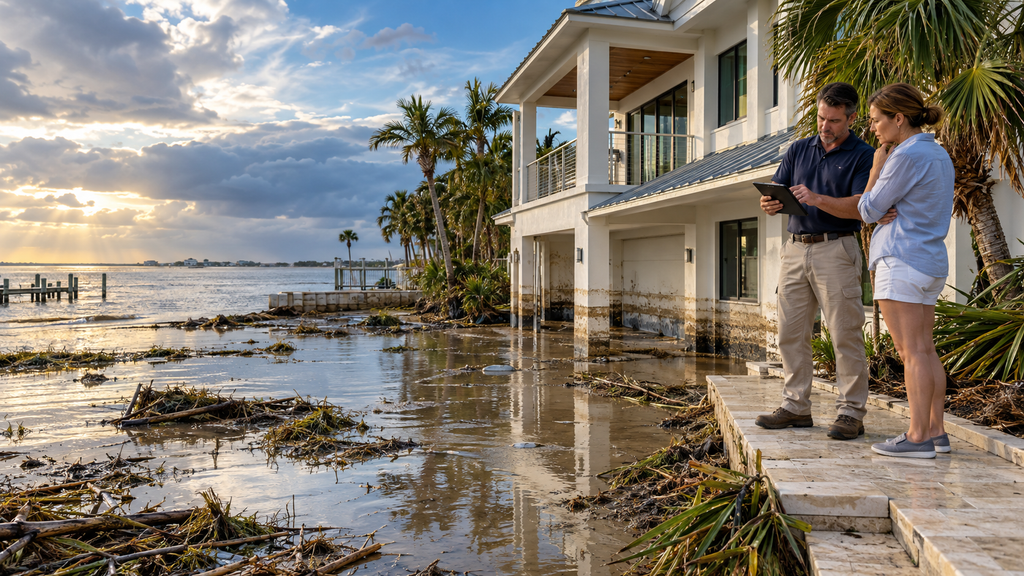
When a hurricane approaches Florida, homeowners naturally think about wind, rain, roof damage, and flooding. But one of the most destructive hurricane hazards can be storm surge. This raises an important insurance question: Does homeowners insurance cover storm surge? In most cases, standard homeowners insurance does not cover flood damage caused by storm surge. Storm surge is generally treated as flooding, so coverage for that type of loss usually comes from a separate flood insurance policy rather than a standard homeowners policy. At PICC FLA, we help Florida property owners document and navigate property insurance claims involving hurricanes, floods, wind, roof damage, water intrusion, and other covered losses. When a hurricane causes several types of damage at the same property, determining how each part of the damage occurred can be an important part of the claims process. That distinction matters because a hurricane can cause wind damage and flood damage during the same event, but those losses may fall under...


